Industry Spotlight: Alternative Financing for General Contractors
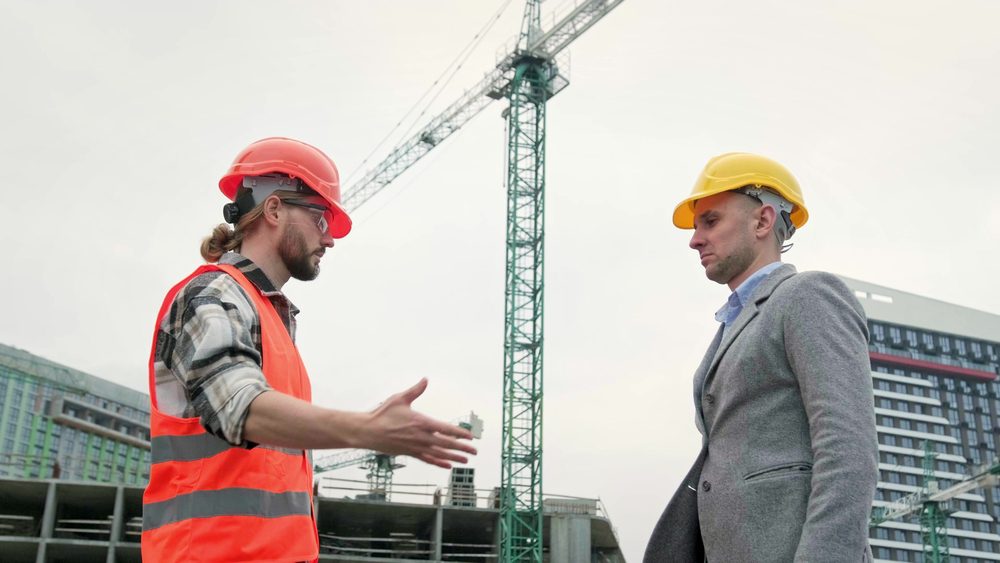
General contractors build the projects that define communities and drive commercial development, and they do it while carrying some of the most demanding cash flow structures in any industry. A GC mobilizes crews and orders materials before the first pay application goes out, manages subcontractor payments on schedules that may not align with owner payments, and carries retainage withheld until project completion. For a contractor running multiple projects at once, the gap between what the business has spent and what it has collected can stretch across months and millions of dollars.
The Cash Flow Structure of General Contracting
Construction billing runs on a monthly application for payment cycle. A GC submits a pay application to the owner or developer at the end of each billing period, documenting the work completed that month and requesting payment for that percentage of the contract. The owner reviews the application, approves the amount, and issues payment, a process that adds another 30 to 60 days to the timeline after the billing period closes.
Throughout that cycle, the GC is paying subcontractors and suppliers on their own schedules. Material suppliers expect payment within 30 days of delivery. Subcontractors submit their own invoices to the GC and expect payment within a similar window. A general contractor receiving payment from the owner on net-60 terms while paying subs and suppliers on net-30 is extending credit to the project owner with its own operating capital.
Why Conventional Credit Misses the Business Model
General contracting is project-based, and that structure creates challenges for conventional lenders. Revenue can concentrate on a small number of projects and clients, which triggers concentration concerns in a standard credit underwriting. The balance sheet of a growing GC may look thin relative to the volume of work it manages, because the business is asset-light outside of equipment and the capital cycles through the project rather than building on the balance sheet.
Accounts Receivable Financing for General Contractors
AR financing converts submitted pay applications into working capital without waiting on the owner’s payment cycle. For a general contractor that has submitted a billing for completed work, AR financing advances a percentage of that pay application within days, giving the GC the cash to pay subcontractors and suppliers while the owner processes payment on their end.
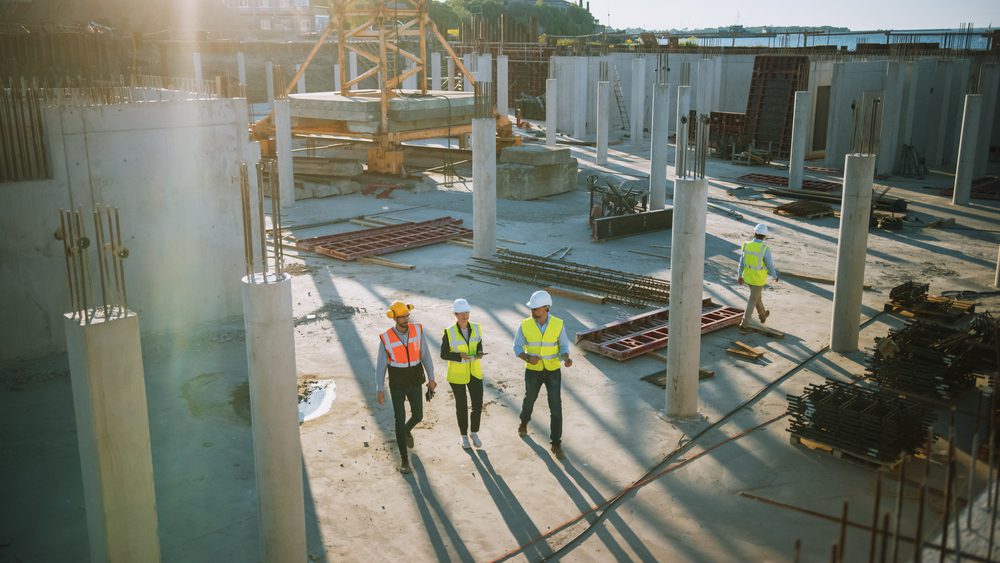
The creditworthiness of the owner or developer on the other side of the pay application is the anchor of the AR financing decision. A GC working for established developers, corporate real estate owners, or public agencies has account debtors whose payment obligations a financing company can assess with confidence. That account debtor quality supports the advance regardless of where the GC’s own balance sheet sits.
Invoice Factoring for General Contractors
Invoice factoring gives general contractors a way to sell outstanding pay applications to a factoring company in exchange for an immediate cash advance. The factoring company takes on the receivable, collects from the project owner when payment comes due, and remits the remaining balance to the GC minus its fee. The GC receives working capital tied to completed work without waiting on the owner’s billing cycle.
For a general contractor managing multiple active projects with different owners and different payment timelines, factoring provides a consistent source of working capital that scales with billing volume rather than sitting at a fixed credit limit. A contractor that has a strong project backlog but a financial profile that falls outside conventional lending thresholds can access factoring based on the creditworthiness of the owners paying the invoices rather than its own credit history.
What This Means for General Contractors
The cash flow demands of general contracting are structural and predictable. Monthly billing cycles, 30 to 60 day payment terms, subcontractor obligations that run ahead of owner receipts, and retainage held through project completion create a working capital gap that exists on every project regardless of how the job is managed. Alternative financing tools built around pay applications and construction receivables address that gap where it lives, between the work being completed and the payment arriving.
Latest Blogs
-
Can I Get Alternative Business Funding With Bad Credit?
A low credit score closes some doors. It does not close all of them. If you’ve been turned down for a business loan because of your credit score, you’re not alone, and you’re not out of options. According to the Federal Reserve’s 2024 Small Business Credit Survey, 29 percent of business loan applicants were denied…
-
Industry Spotlight: Alternative Financing for Telecommunications Contractors
Telecommunications contractors build and maintain the infrastructure that carries voice, data, and broadband across commercial buildings, residential developments, and public networks. Tower erection, fiber optic installation, underground conduit work, distributed antenna systems, and last-mile broadband deployment all move through contractors who mobilize crews, procure materials, and begin work weeks or months before the billing cycle…
-
Industry Spotlight: Alternative Financing for Truck and Auto Parts Distributors
Truck and auto parts distributors supply the components that keep commercial fleets, repair shops, dealerships, and municipal vehicle operations on the road. OEM and aftermarket parts move from manufacturers through distributors to fleet operators, trucking companies, commercial repair facilities, and government vehicle maintenance operations, and those buyers expect fast delivery and reliable inventory availability. The…
-
Industry Spotlight: Alternative Financing for Electrical Equipment Distributors
Electrical equipment distributors supply the components that keep construction projects moving and industrial facilities running. Switchgear, transformers, breakers, panels, wiring, conduit, motors, and lighting products move from manufacturers through distributors to electrical contractors, construction companies, industrial plants, utilities, and municipalities. The distributor sits in the middle of that supply chain, purchasing inventory from manufacturers on…