When Your Business Needs More Than a Bank Loan
Business financing options have expanded significantly beyond traditional bank lending. Understanding when alternative financing structures may be appropriate can help businesses address working capital constraints and support growth objectives more effectively.
When Traditional Bank Approval Processes Create Constraints
Traditional bank lending typically requires extensive credit history, substantial collateral, and conservative financial projections. The approval process often extends several weeks to months, which can delay time-sensitive business opportunities such as large contract fulfillment, inventory procurement, or early-payment supplier discounts.
Alternative financing providers typically operate with shorter approval timelines and evaluate creditworthiness based on cash flow performance and growth metrics rather than exclusively on historical financial statements. This approach can be particularly relevant for businesses with strong operational fundamentals but limited credit history or those pursuing aggressive but sustainable growth strategies.
When Payment Timing Creates Working Capital Gaps
Industries with extended payment terms—such as construction, wholesale distribution, and professional services—frequently experience timing mismatches between accounts payable obligations and accounts receivable collections. This can strain liquidity even in profitable operations.
Accounts receivable financing and invoice factoring convert outstanding invoices into immediate working capital. The global factoring market is projected to expand from $4.4 trillion in 2024 to $7.3 trillion by 2031, reflecting increased adoption across sectors facing payment timing challenges.
These financing mechanisms are particularly applicable when:
- Regular monitoring of aging receivables is in place
- Client payment terms extend beyond operational expense cycles
- Inventory procurement timing requires alignment with sales cycles
When Revenue Growth Outpaces Available Capital
Rapid business expansion can create capital requirements that exceed existing credit facilities. This includes costs associated with facility expansion, payroll increases, inventory scaling, and equipment acquisition.
Revenue-based financing and flexible credit facilities scale proportionally with business performance, providing increased liquidity as revenue grows. This structure is commonly utilized by technology companies post-product launch or manufacturers securing national distribution agreements.
Prior to implementing growth financing, businesses should:
- Model multiple revenue scenarios (conservative, expected, optimistic)
- Establish favorable vendor payment terms
- Maintain cash reserves sufficient for minimum one full payroll cycle
When Credit History Limits Access to Traditional Financing
Limited operating history or previous credit challenges can restrict access to conventional bank products. However, businesses may still possess valuable assets including strong receivables, confirmed purchase orders, or long-term contracts.
Alternative financing providers often emphasize current operational performance and asset quality over historical credit metrics. This enables:
- Working capital access without traditional collateral requirements
- Business continuity during credit profile improvement
- Payment structures aligned with actual cash receipt timing
To strengthen business credit profiles over time: review D-U-N-S and Experian commercial reports quarterly, address reporting errors promptly, and establish vendor accounts that report payment performance to credit bureaus.
When Standard Loan Structures Don’t Align With Business Cycles
Fixed-payment term loans can create cash flow pressure for businesses with extended production cycles, seasonal revenue patterns, or project-based income. Industries such as aerospace manufacturing, event management, or agriculture often experience revenue concentration in specific periods.
Alternative financing structures offer greater flexibility through:
- Payment schedules aligned with revenue timing
- Industry-specific covenant structures
- Facilities that automatically scale with sales performance
- Flexible exit provisions
Before committing to any financing arrangement, evaluate:
- Payment timing relative to cash receipt patterns
- Covenant appropriateness for industry norms
- Automatic scaling capability with revenue growth
- Exit terms and associated costs
Alternative Financing Applications By Region and Sector
Midwest Manufacturing Equipment financing and AR factoring support operations with 60-90 day payment terms from automotive and industrial clients, bridging the gap between raw material purchases and payment receipt.
Texas Energy Services Invoice factoring on oilfield services invoices maintains operational cash flow during project payment delays, covering crew payroll without extended payment waiting periods.
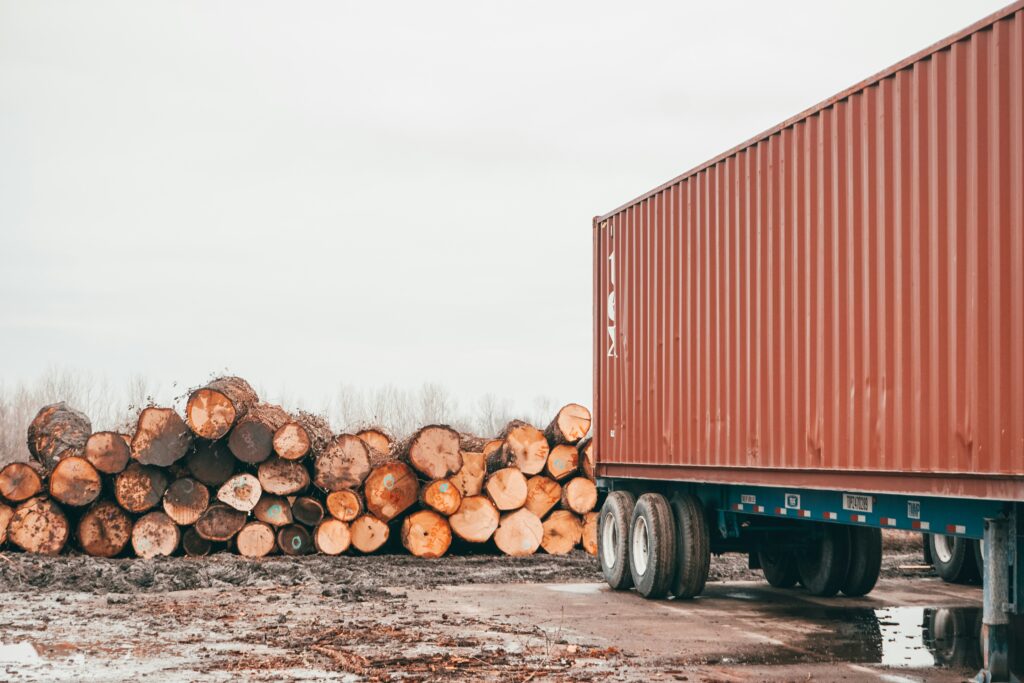
Pacific Northwest Logistics Freight invoice conversion to immediate working capital supports fuel costs, equipment maintenance, and driver compensation while awaiting net-30 or net-60 shipper payments.
Southern Agriculture Pre-season financing covers seed and fertilizer procurement costs before planting cycles.
Northeast Retail Combined invoice factoring and revolving credit facilities manage seasonal revenue fluctuations.
California Technology Revenue-based financing tied to monthly recurring revenue provides growth capital without equity dilution.
Market Growth Indicators
The expansion of alternative financing reflects changing business capital requirements. The global factoring market is projected to grow from $4.4 trillion (2024) to $6 trillion (2031). The broader alternative lending platforms are projected to reach $14.5 billion by 2030.
This growth indicates increasing business adoption of alternative financing as a strategic capital solution rather than solely as a backup option to traditional banking.
Strategic Considerations
Identifying financing needs early, whether related to bank approval timing, cash flow gaps, rapid growth, credit constraints, or inflexible debt structures, enables proactive capital planning before operational challenges emerge.
Alternative financing mechanisms including accounts receivable financing, invoice factoring, and revenue-based advances address specific working capital challenges that traditional bank products may not accommodate effectively. Partnering with specialized financing providers can provide access to diverse lender networks and industry-specific expertise that improves approval rates and terms appropriateness.
Evaluating financing options based on business-specific cash flow patterns, growth trajectories, and industry characteristics supports more effective capital structure decisions and operational scalability.
Latest Blogs
-
Can I Get Alternative Business Funding With Bad Credit?
A low credit score closes some doors. It does not close all of them. If you’ve been turned down for a business loan because of your credit score, you’re not alone, and you’re not out of options. According to the Federal Reserve’s 2024 Small Business Credit Survey, 29 percent of business loan applicants were denied…
-
Industry Spotlight: Alternative Financing for Telecommunications Contractors
Telecommunications contractors build and maintain the infrastructure that carries voice, data, and broadband across commercial buildings, residential developments, and public networks. Tower erection, fiber optic installation, underground conduit work, distributed antenna systems, and last-mile broadband deployment all move through contractors who mobilize crews, procure materials, and begin work weeks or months before the billing cycle…
-
Industry Spotlight: Alternative Financing for Truck and Auto Parts Distributors
Truck and auto parts distributors supply the components that keep commercial fleets, repair shops, dealerships, and municipal vehicle operations on the road. OEM and aftermarket parts move from manufacturers through distributors to fleet operators, trucking companies, commercial repair facilities, and government vehicle maintenance operations, and those buyers expect fast delivery and reliable inventory availability. The…
-
Industry Spotlight: Alternative Financing for Electrical Equipment Distributors
Electrical equipment distributors supply the components that keep construction projects moving and industrial facilities running. Switchgear, transformers, breakers, panels, wiring, conduit, motors, and lighting products move from manufacturers through distributors to electrical contractors, construction companies, industrial plants, utilities, and municipalities. The distributor sits in the middle of that supply chain, purchasing inventory from manufacturers on…