Smart Business: 7 Ways To Get Your Cash Flow Under Control
Cash flow challenges affect businesses of all sizes, but they can really cripple small and medium-sized businesses (SMBs). Even profitable businesses can face serious operational constraints when revenue timing doesn’t align with expense schedules. The good news? Most cash flow problems can be addressed through strategic planning and the right financial tools.
Here are CapitalNetwork‘s seven proven strategies to strengthen your cash flow and build a more resilient business.
1. Convert Outstanding Invoices to Immediate Cash with AR Financing
When clients take up to three months to pay invoices, your working capital becomes trapped in accounts receivable. Accounts receivable financing solves this by providing immediate access to 80-90% of your outstanding invoice value, typically within days.
This approach is particularly valuable when you’re pursuing growth opportunities that require immediate investment, managing seasonal revenue fluctuations, or simply maintaining consistent operations while waiting for client payments. Because it represents an advance on money already earned rather than debt, it doesn’t create long-term liabilities on your balance sheet.
2. Accelerate Your Collection Cycle
The faster you collect payments, the healthier your cash flow. Start by making it easy for customers to pay through multiple channels like credit cards, ACH transfers, mobile payments, and online portals. The fewer friction points in the payment process, the quicker money arrives.
Consider offering modest early payment discounts (such as 2% off for payment within 10 days) to incentivize prompt payment. For clients with consistent payment delays, require deposits upfront or implement milestone-based billing for longer projects. These changes shift some cash flow burden back to customers rather than absorbing it entirely yourself.
3. Optimize Your Payment Timing to Vendors
While accelerating customer payments, strategically manage your own payables. Take full advantage of vendor payment terms without damaging relationships. If terms allow 30 days, don’t pay in 15 days unless there’s a compelling discount.
Review all vendor contracts and negotiate extended payment terms where possible. Many suppliers are willing to offer net-45 or net-60 terms to valued customers, especially if you commit to a consistent volume or longer-term agreements.
Set up your accounts payable system to schedule payments on the due date rather than when invoices arrive. This keeps your cash working for you as long as possible while maintaining good vendor relationships.
4. Reduce Inventory and Overhead Costs
Excess inventory represents cash sitting on shelves instead of working for your business. Analyze your inventory turnover and identify slow-moving items. Discount them aggressively if necessary to convert them back to cash.
Implement just-in-time inventory management where feasible, ordering materials closer to when you actually need them rather than stockpiling. This reduces both inventory carrying costs and the cash tied up in materials.
Beyond inventory, scrutinize all operating expenses. Can you negotiate better rates on rent, insurance, or utilities? Are there subscriptions or services you’re paying for but rarely using? Can you reduce travel expenses through better planning or virtual alternatives? Every dollar you save by eliminating unnecessary expenses is a dollar available for critical operations.
5. Establish a Business Line of Credit
A business line of credit functions as a financial safety net, providing access to funds when unexpected expenses arise or opportunities emerge. Unlike term loans, you only pay interest on the amount you actually draw, and you can borrow and repay flexibly as needs change.
The critical timing consideration is to establish your line of credit before you need it, while business is performing well. Banks tighten lending standards during economic downturns, making it much harder to secure credit exactly when you need it most. By setting up a credit facility during good times, you ensure access to capital when challenges arise.
6. Separate Business and Personal Finances
Mixing personal and business finances creates confusion about your true cash position and complicates financial planning. Open dedicated business checking and savings accounts to clearly separate business operations from personal expenses.
This separation provides several benefits including clearer visibility into actual business cash flow, simplified tax preparation and bookkeeping, improved credibility with lenders and vendors, and protection of personal assets from business liabilities.
Once separated, use business accounts exclusively for business transactions. Pay yourself a regular salary or owner’s draw rather than pulling money irregularly from business accounts. This creates predictability in both your business and personal cash flow.
7. Build and Maintain Cash Reserves
Even modest cash reserves provide crucial protection against unexpected challenges. Set aside a percentage of revenue into a separate business savings account designated for emergencies and opportunities.
These reserves serve multiple purposes like covering unexpected expenses without disrupting operations, taking advantage of time-sensitive opportunities, bridging gaps during seasonal slowdowns, and reducing stress during client payment delays.
Maintain reserves in interest-bearing accounts when possible to generate modest returns while keeping funds accessible. As reserves grow, they also improve your business’s creditworthiness and provide options beyond external financing.
Taking Action
Cash flow management isn’t a one-time fix but an ongoing discipline. The businesses that thrive are those that monitor cash flow consistently, take proactive steps to optimize timing, and establish financial tools before urgent needs arise.
Start by implementing the strategies most relevant to your current situation. If client payment delays are your primary challenge, focus on AR financing and collection acceleration. If seasonal patterns create problems, prioritize building reserves and establishing credit facilities.
Our SMB cash flow experts here at CapitalNetwork are ready to help you with your cash flow needs.
This post is part of our Smart Business series — practical financial guidance for small business owners navigating growth, cash flow, and everything in between.
Latest Blogs
-
Can I Get Alternative Business Funding With Bad Credit?
A low credit score closes some doors. It does not close all of them. If you’ve been turned down for a business loan because of your credit score, you’re not alone, and you’re not out of options. According to the Federal Reserve’s 2024 Small Business Credit Survey, 29 percent of business loan applicants were denied…
-
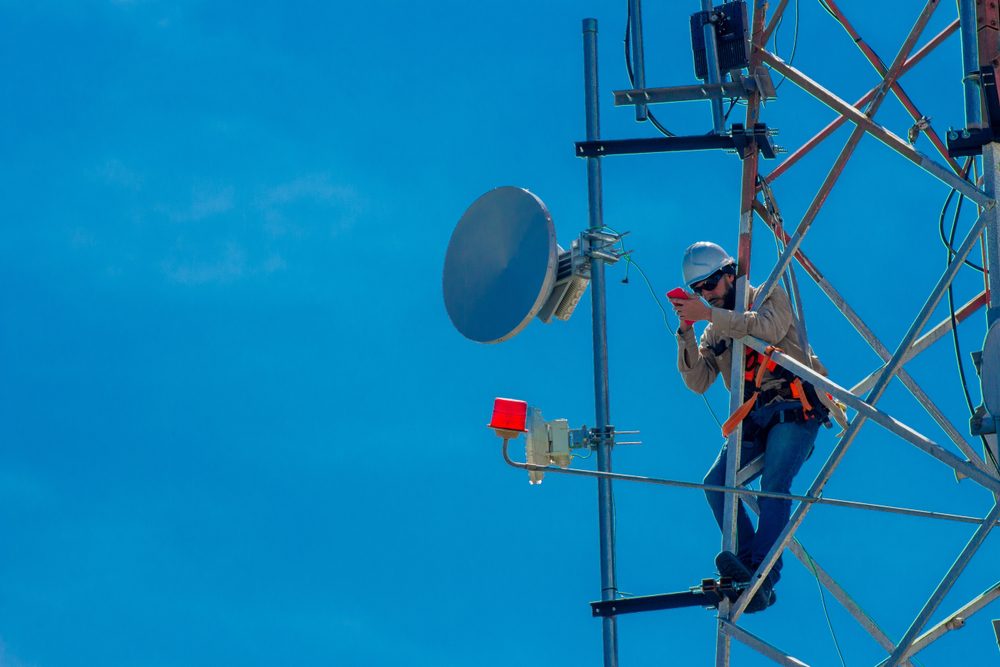
Industry Spotlight: Alternative Financing for Telecommunications Contractors
Telecommunications contractors build and maintain the infrastructure that carries voice, data, and broadband across commercial buildings, residential developments, and public networks. Tower erection, fiber optic installation, underground conduit work, distributed antenna systems, and last-mile broadband deployment all move through contractors who mobilize crews, procure materials, and begin work weeks or months before the billing cycle…
-
Industry Spotlight: Alternative Financing for Truck and Auto Parts Distributors
Truck and auto parts distributors supply the components that keep commercial fleets, repair shops, dealerships, and municipal vehicle operations on the road. OEM and aftermarket parts move from manufacturers through distributors to fleet operators, trucking companies, commercial repair facilities, and government vehicle maintenance operations, and those buyers expect fast delivery and reliable inventory availability. The…
-
Industry Spotlight: Alternative Financing for Electrical Equipment Distributors
Electrical equipment distributors supply the components that keep construction projects moving and industrial facilities running. Switchgear, transformers, breakers, panels, wiring, conduit, motors, and lighting products move from manufacturers through distributors to electrical contractors, construction companies, industrial plants, utilities, and municipalities. The distributor sits in the middle of that supply chain, purchasing inventory from manufacturers on…