Industry Spotlight: Alternative Financing for Concrete Contractors
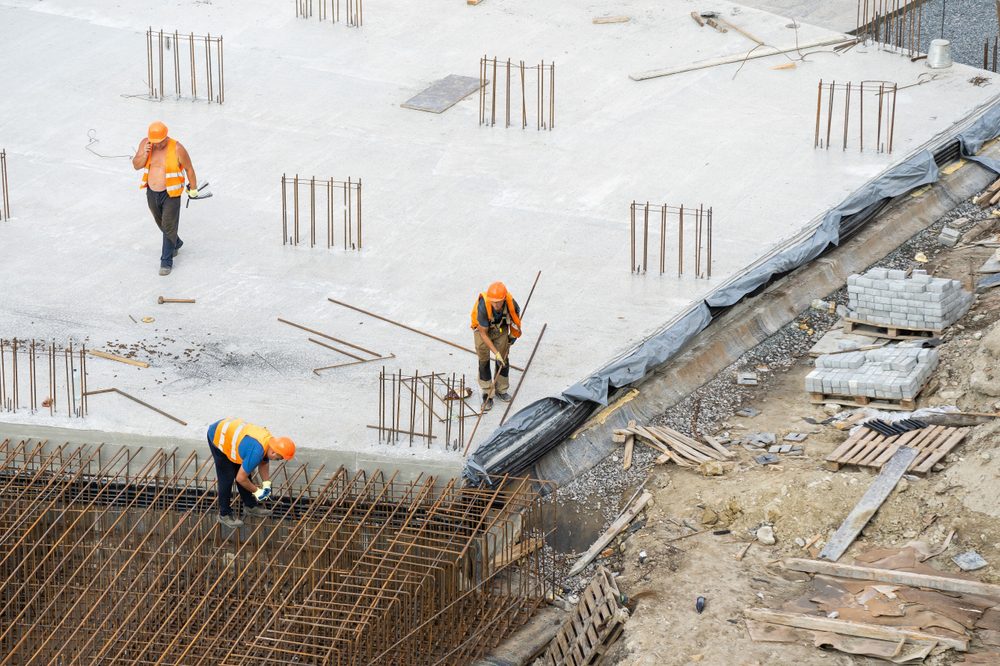
Concrete contractors are among the first trades on a commercial construction site and among the last to see payment for their work. Foundation crews, slab contractors, flatwork specialists, and concrete finishing operations all share a common financial challenge in which material costs are immediate, labor runs weekly, and the billing and payment cycle in commercial construction runs 30 to 60 days behind the work.
For a concrete contractor managing multiple pours across several active projects, the gap between what the business has spent and what it has collected can represent a significant amount of working capital tied up in completed work.
The Cash Flow Structure of Concrete Contracting
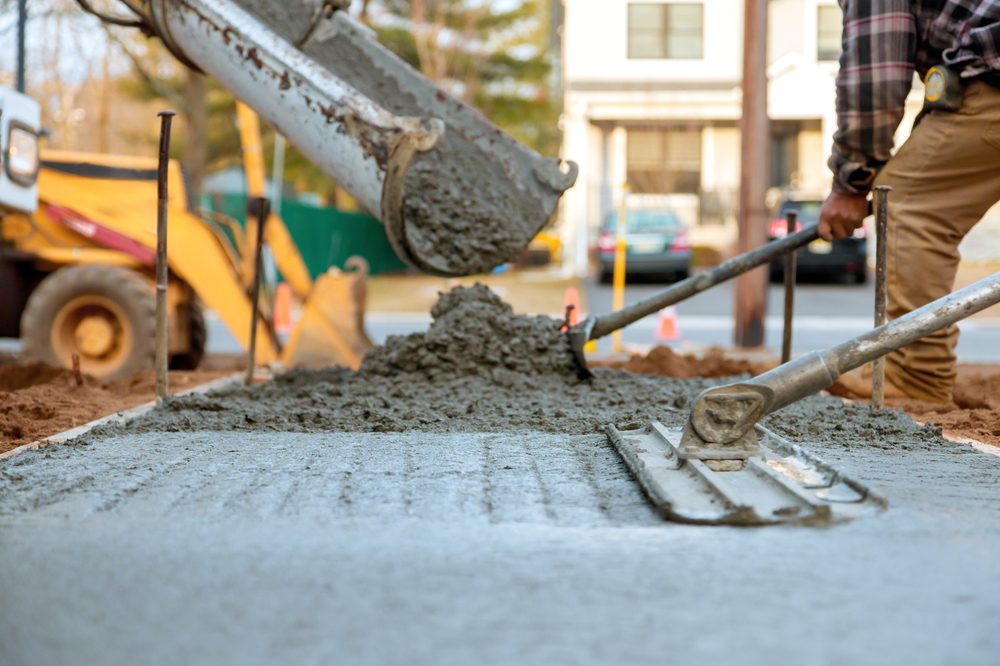
Concrete work is front-loaded with cost in ways that few other trades experience as sharply. Ready-mix concrete is delivered to the job site and poured on the day it is ordered. The concrete supplier expects payment on short terms, and COD or net-30 is common in the ready-mix market. The concrete contractor absorbs that material cost at the point of pour, before the work is invoiced and long before the general contractor processes a pay application.
Accounts Receivable Financing for Concrete Contractors
AR financing converts submitted pay applications into working capital without waiting on the general contractor’s payment cycle. A concrete contractor that has completed a billing period and submitted its monthly pay application to the GC can receive an advance against that application within days, giving the business cash to cover material purchases, crew wages, and equipment costs while the payment process works through the GC’s approval cycle.
The creditworthiness of the account debtor supports the advance. A concrete contractor working for an established regional or national general contractor has an account debtor whose payment obligations a financing company can evaluate with confidence. That account debtor quality supports the advance regardless of where the concrete contractor’s own balance sheet sits relative to its working capital needs.
Lien rights in construction are a factor that matters in any AR financing arrangement involving construction receivables. The mechanics lien process, conditional and unconditional lien waivers, and preliminary notices vary by state and affect the collectibility of construction invoices. A financing company with construction industry experience understands how to work within that framework.
Invoice Factoring for Concrete Contractors
Invoice factoring gives concrete contractors a way to sell completed pay applications and invoices to a factoring company in exchange for an immediate advance. The factoring company collects from the general contractor or project owner when payment comes due and remits the remaining balance minus its fee. The concrete contractor receives working capital tied to completed pours rather than waiting through the GC’s billing cycle.
Factoring suits concrete contractors that are growing faster than their credit capacity supports, managing multiple active projects with different billing timelines, or working with general contractors whose payment practices run toward the longer end of the net-30 to net-60 range. Because factoring approval centers on the creditworthiness of the GC or project owner rather than the concrete contractor’s own financial profile, a contractor with strong commercial GC relationships can access factoring based on those relationships rather than on its own balance sheet.
For concrete contractors whose work includes both commercial subcontract work and direct owner contracts, factoring can cover both billing types under a single working capital facility.
Equipment Financing for Concrete Operations
Concrete pumps, mixer trucks, and forming systems represent significant capital investment for a growing concrete contractor. Equipment financing spreads those acquisition costs over time, preserving operating liquidity for ready-mix purchases and payroll during the active season. Sale-leaseback arrangements give contractors that own their equipment outright a way to convert that equipment equity into working capital while retaining full operational use of the assets on active job sites.
A concrete contractor adding a pump truck to take on larger commercial pours can use equipment financing to add that capacity without absorbing the acquisition cost against the operating cash that funds weekly concrete purchases.
What This Means for Concrete Contractors
The cash flow challenge in concrete contracting is structural and repeating. Ready-mix is purchased before billing is possible, labor runs ahead of collections, and the construction payment cycle adds weeks between invoice submission and payment receipt. Alternative financing tools built around pay applications and equipment give concrete contractors a way to manage that gap and take on larger projects without depending on a conventional credit line that may not flex with the pace of active commercial work.
CapitalNetwork works with concrete contractors and construction subcontractors to identify the right financing structure for the scale and rhythm of the operation. If outstanding pay applications are creating material purchasing pressure or a new project requires concrete investment before the first billing cycle, this is the right time to explore what AR financing and factoring can do for your business.
Latest Blogs
-

Industry Spotlight: Alternative Financing for Drug and Pharmaceutical Wholesalers
Pharmaceutical wholesalers distribute prescription drugs, specialty medications, over-the-counter products, and medical supplies to pharmacies, hospitals, health systems, nursing homes, and clinics. The buyers on the receiving end of those deliveries are among the most creditworthy account debtors in any industry. The problem is not whether they will pay. Hospital systems and regional pharmacy chains have…
-

Industry Spotlight: Alternative Financing for Air Compressor Services Companies
Air compressor service companies sell, rent, install, and maintain the compressed air systems that manufacturing plants, construction sites, hospitals, food processing facilities, and automotive operations depend on to run. The business runs across two revenue models at once, with recurring rental and service contract billing generating monthly invoices on one track and project-based installation and…
-

Industry Spotlight: Alternative Financing for Food Distributors
Food distributors move product from manufacturers, farms, and processors to the restaurants, grocery chains, institutional buyers, and food service operations that feed people every day. The margins are thin, the inventory is perishable, and the cash flow structure runs in two directions at once. Suppliers want payment on short terms, shorter than the thirty to…
-

Industry Spotlight: Alternative Financing for Graphic Design Studios
Graphic design studios and agencies that serve corporate clients, marketing departments, publishers, and retailers operate on a project economy where the product is creative work and the billing cycle is whatever the client’s accounts payable department decides it is. A design team builds a brand identity, produces a packaging system, or delivers a campaign’s worth…